We use cookies to improve your experience. By using BondbloX, you agree to our use of cookies.
Bond Market News
Geopolitical Risks Outweigh Soft Jobs Report
August 11, 2026

– Amruth S
US Treasury yields were higher by 4-5bp across the curve on Monday. Late last week, US NFP for July saw a negative surprise, coming in at -23k vs. expectations of 80k. Average Hourly Earnings YoY rose by 3.2%, lower than the surveyed 3.5%. Also, the Unemployment Rate came in at 4.1%, lower than expectations of 4.2%. Despite a soft jobs report, geopolitical risks continue to weigh on the US Treasuries. US President Donald Trump said that he is demanding compensation from Iran for the latter’s actions over decades. Iran on the other hand said that reopening the Strait of Hormuz depends on the US lifting sanctions, and meeting a number of other conditions including removing naval blockades and compensating for war damage. Separately, Cleveland Fed President Beth Hammack noted that “some number” of rate hikes may be needed as a 25bp hike may not do a “whole lot to the economy”. However, she added, “I don’t want to prejudge what that number is going to be.” Hammack was among the three Fed members who dissented in July’s FOMC 9-3 vote to keep rates on hold.
Looking at equity markets, the S&P ended flat while the Nasdaq closed and 0.3% lower. US IG CDS spreads were 1bp wider, while HY CDS spreads widened by 3.9bp. European equity markets ended mixed. European IG CDS spreads were 0.4bp wider, and Crossover spreads widened by 1.7bp. Asian equity markets have opened mixed this morning. Asia ex-Japan CDS spreads were flat.
Rating Changes
- Griffon Corp. Upgraded To ‘BB’ On Lower Leverage Following Divestitures, Outlook Stable; Debt Rated
- Moody’s Ratings upgrades Panasonic to A3; outlook stable
- Moody’s Ratings upgrades Benin’s ratings to Ba3, changes outlook to stable
- Aston Martin Outlook Revised To Negative; Affirmed At ‘CCC+’; Senior Secured Notes Downgraded To ‘CCC’
- Fitch Places Telecom Italia on Rating Watch Positive Following Poste Italiane Bid Approval
- Beazer Homes USA Inc. Ratings On CreditWatch Positive On Acquisition By Dream Finders Homes Inc.
Term of the Day: Trigger (for AT1s)
Triggers are an important feature of AT1s bonds and define when the loss absorption mechanism is activated. Triggers can either be mechanical or discretionary. Mechanical triggers are numerically defined and most commonly refer to the bank’s capital ratio level. Discretionary triggers, also known as point of non-viability (PONV) triggers are based on supervisors’ judgement of the bank’s solvency position. On occurrence of a trigger event, a AT1’s loss absorption mechanism kicks in, which may include a conversion to equity or a principal write-down, both of which boost the bank’s capital position.
Talking Heads
On Seeing AI Helping Buoy GDP Even as Hiring Slows – Rick Rieder, BlackRock
“I just think hiking doesn’t make a lot of sense today… In bonds, we’re trying to be as boring as you could be”
On Boosting Tech Bond Sales Outlook as AI Debt Binge Expands – JPMorgan
This is “reinforcing our expectation that debt-fueled external financing will remain a defining feature of the AI investment cycle for years to come… We do not believe we are through the supply hurdle this year, likely far from it”
On Fed Split on Rate Hikes Deepening
James Egelhof, chief US economist at BNP Paribas
“The data has been ambiguous on which one of these stories is actually playing out”
Claudia Sahm, New Century Advisors
“The Fed’s tools are best suited for smoothing out the business cycle and what’s really driving the shifts we see in the aggregate data is a lot of structural shifts under the hood”
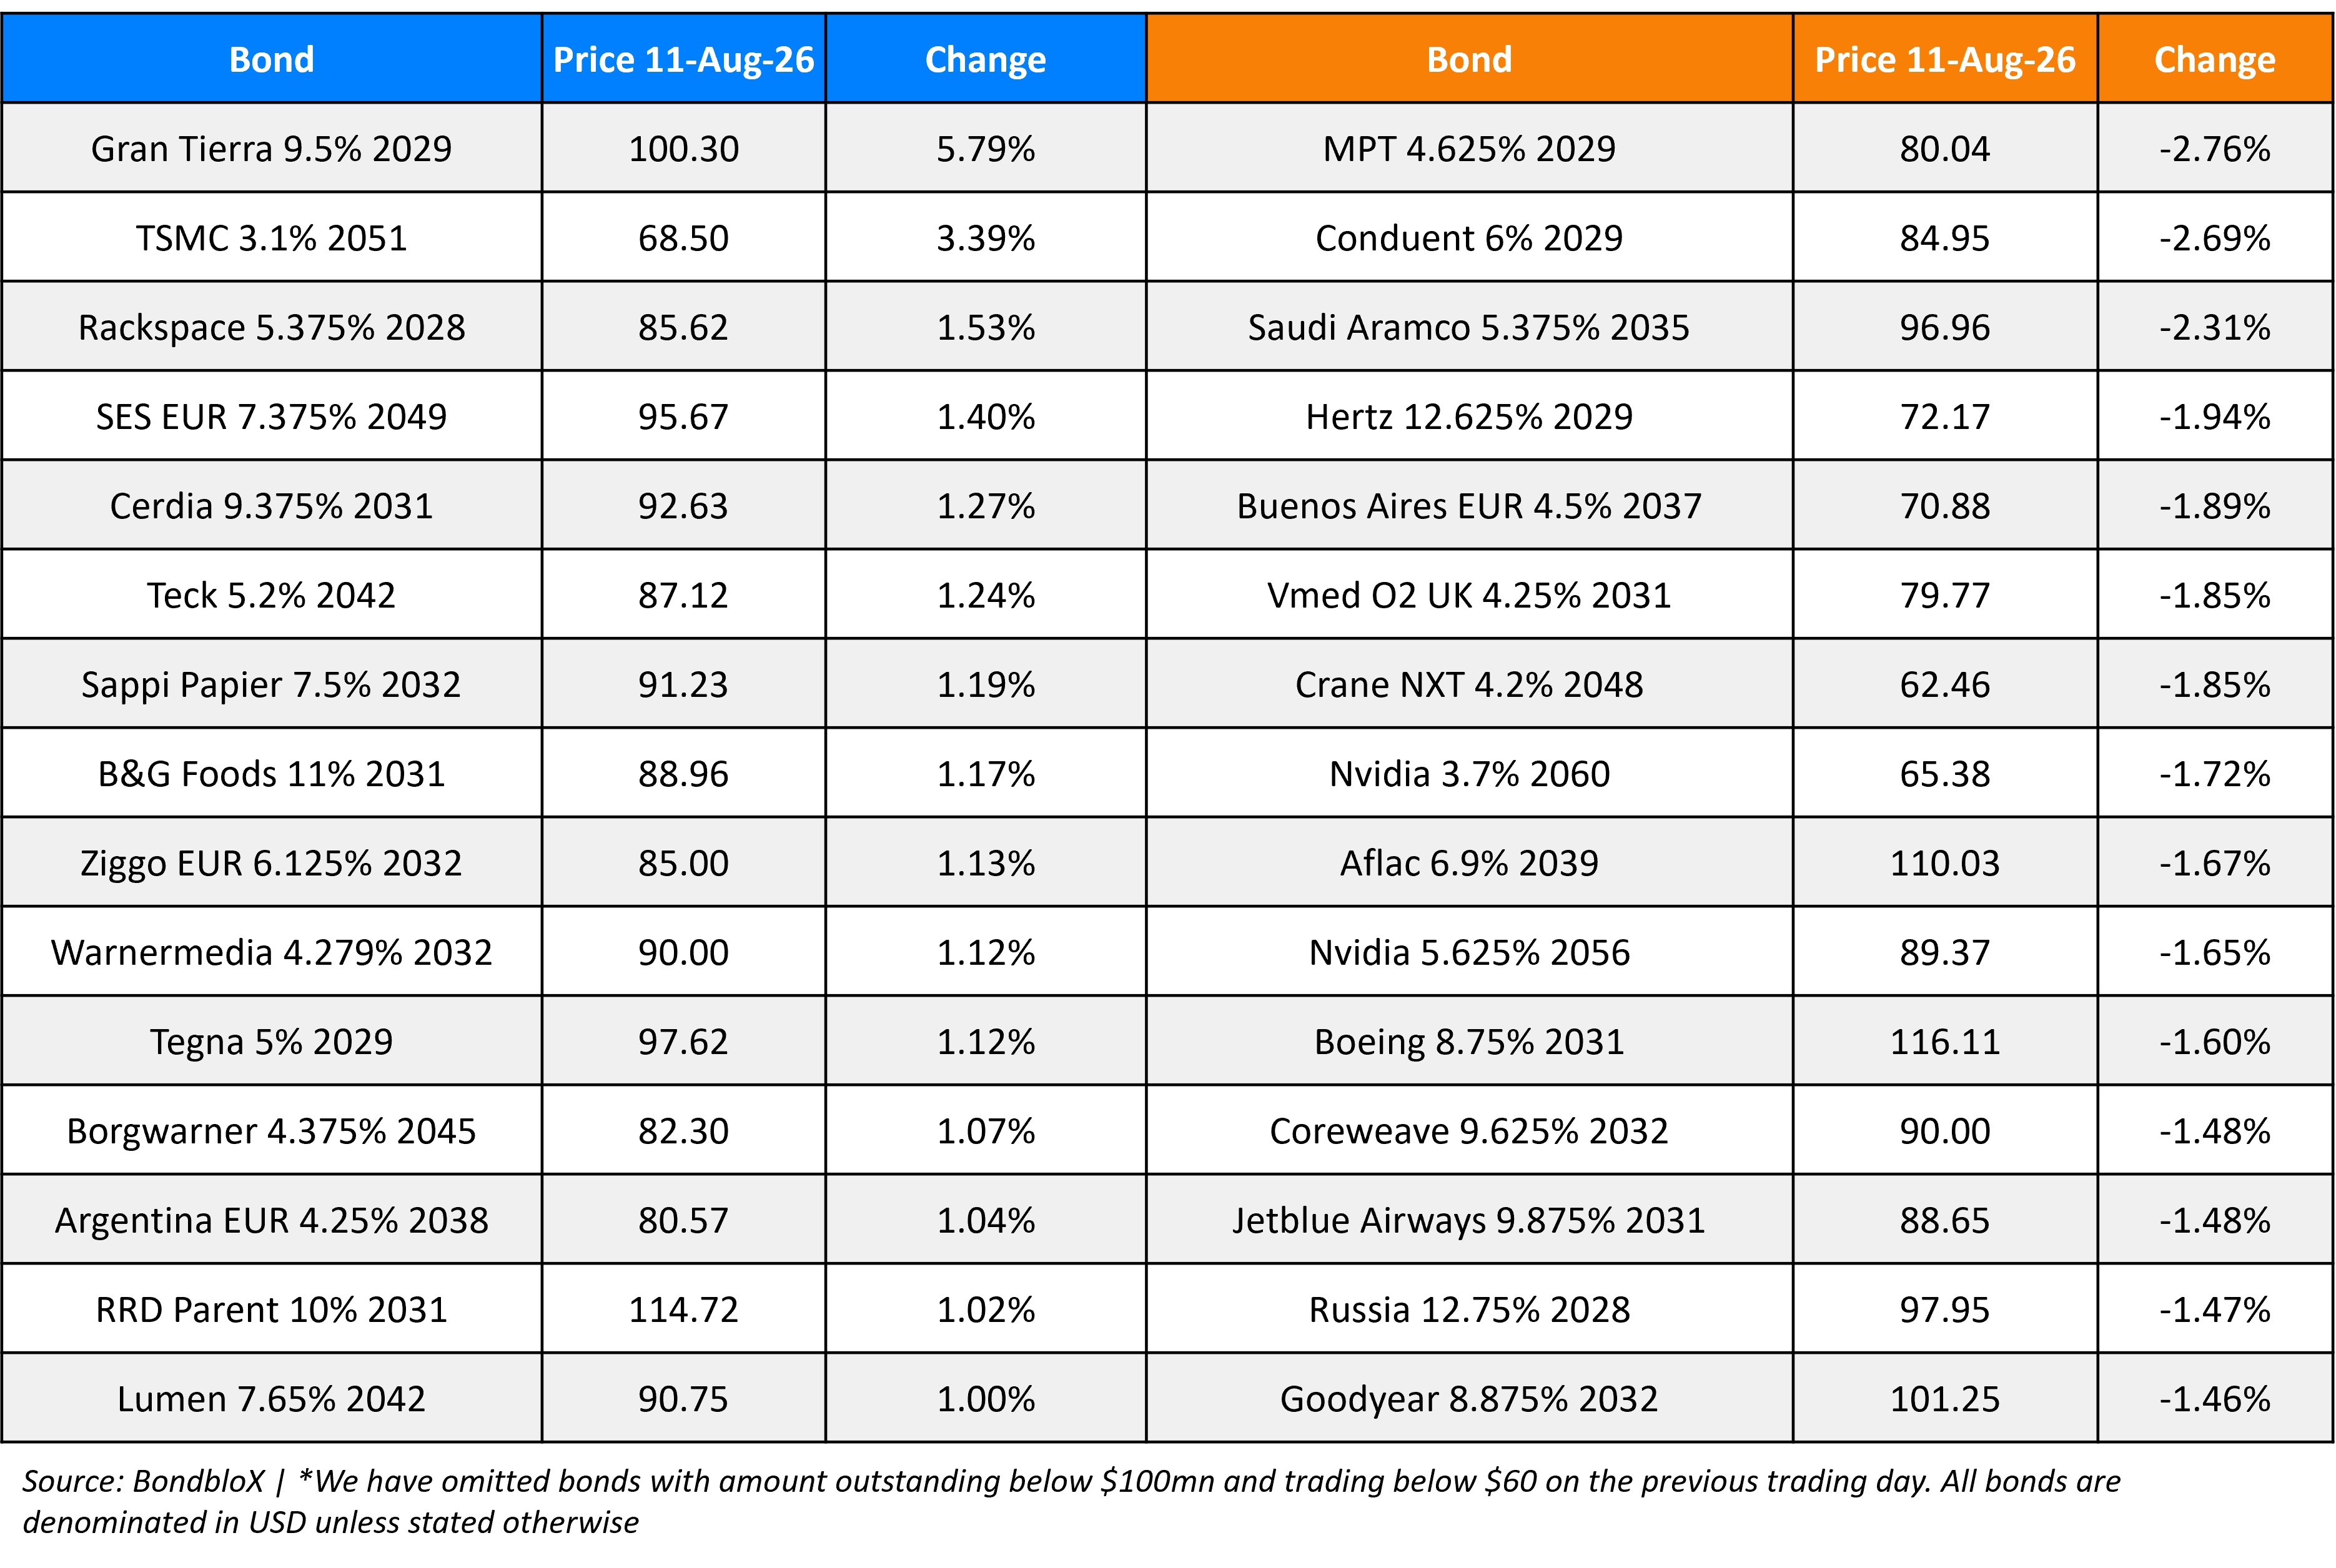
Top Gainers and Losers- 11-Aug-26*
Go back to Latest bond Market News
Related Posts: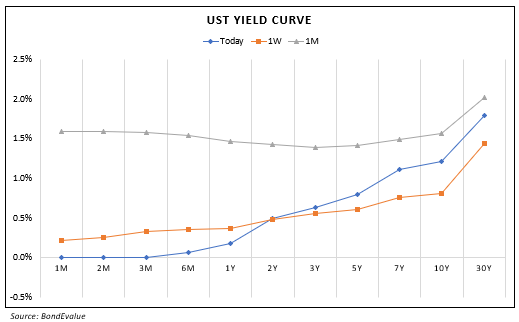
Our Awards
BondbloX Pte. Ltd. is regulated by the Monetary Authority of Singapore as a Recognised Market Operator ("RMO") and exempted from Section 49(1) of the Securities and Futures Act (Cap. 289) ("SFA") under Section 49(7) of the SFA.