We use cookies to improve your experience. By using BondbloX, you agree to our use of cookies.
Bond Market News
Ecuador Upgraded to B by S&P
August 14, 2026
-Vandit P
Ecuador was upgraded by a notch to B from B- by S&P. The upgrade reflects continued execution of politically sensitive fiscal measures and improved access to official and capital market financing. It also reflects Ecuador’s strengthened external position, aided by reduced party fragmentation in Congress under the Noboa administration. The government raised the VAT rate to 15% from 12%, gradually removed energy subsidies, and improved public spending efficiency, helping unlock financing from official creditors. Ecuador raised $5bn from international markets via two bond issuances, of which $3bn went toward liability management. S&P projects a general government deficit of 2.0-2.5% of GDP over the next four years and expects the economy to slow to around 1.5% growth in 2026 before rebounding to about 2.5% annually. Gross international reserves rose to $11.3bn in July 2026 from $4.2bn in January 2024. However, Ecuador’s GDP growth is constrained by oil sector dependence, high spending inflexibility, and exposure to the El Niño weather phenomenon, which threatens hydroelectric generation and agriculture.
Its recently issued 8.75% 2034s were stable at 99.96, yielding 8.76%
Go back to Latest bond Market News
Related Posts: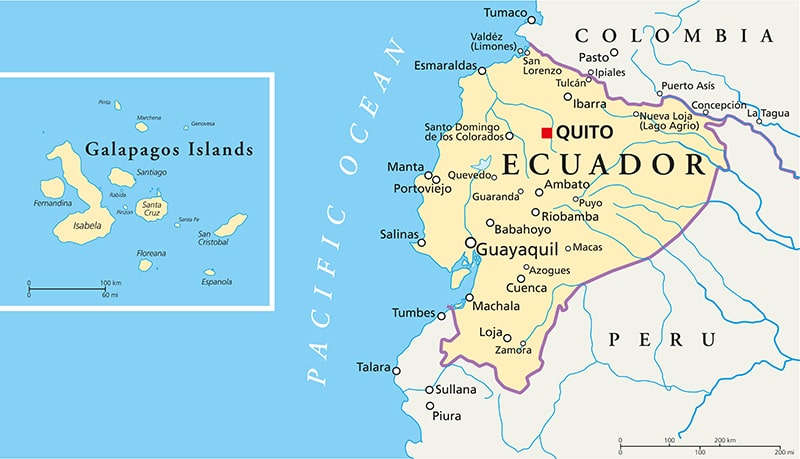
Ecuador Plans Return to Bond Market After 6 years
January 26, 2026
Credit rating boost for Ireland & Portugal: EU inches towards recovery
September 20, 2017
China Refutes S&P Downgrade Action
September 26, 2017
Our Awards
BondbloX Pte. Ltd. is regulated by the Monetary Authority of Singapore as a Recognised Market Operator ("RMO") and exempted from Section 49(1) of the Securities and Futures Act (Cap. 289) ("SFA") under Section 49(7) of the SFA.